

Looking beyond the noise
4 mins to read this article

What matters to you in 30 seconds
- US inflation has put interest rates firmly back in focus. Prices rose more than expected in October, leading markets to anticipate around three Federal Reserve rate increases over the next 12 months.
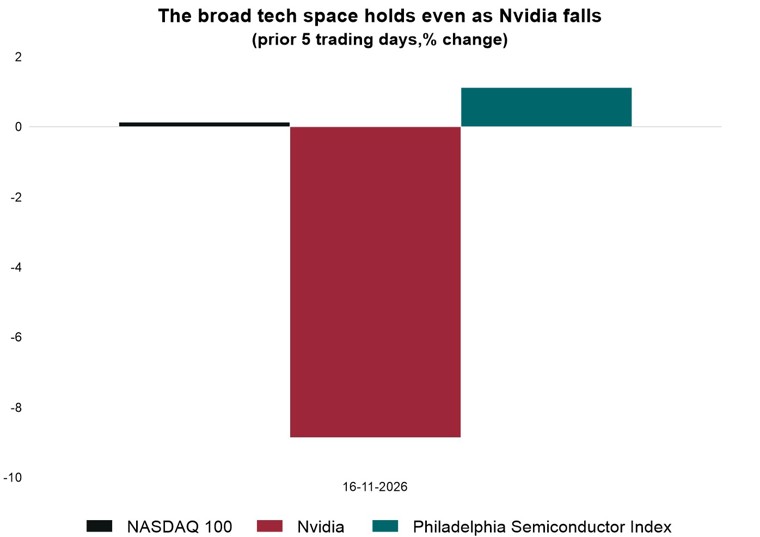
- Technology shares have shown surprising resilience. Artificial Intelligence (AI) related stocks recovered from their earlier sell-off, helped by strong demand for computing infrastructure, even as Nvidia came under significant pressure.
- We are looking beyond the noise. Economic growth and company earnings remain supportive, while higher US Treasury yields have created a more attractive opportunity to add income and resilience to portfolios.
Chart of the week
Source: In house research, LSEG Datastream. Past performance is not a reliable indicator of future returns.
Inflation puts interest rates back in focus
US inflation brought interest rates back to the centre of the market debate this week. Consumer prices rose 0.4% in October, slightly more than expected, while core prices increased 0.3%. Comments from Federal Reserve (Fed) policymakers added to the pressure, pushing Treasury yields higher as markets moved to price roughly three rate increases over the coming 12 months.
We think the Fed may ultimately need to do less.
One reason is oil. Prices have fallen significantly from their recent peak, easing fears of another large energy shock. If that decline proves lasting, it should feed through to inflation, improve household purchasing power and give central banks more room to manoeuvre.
The change in interest-rate expectations has also created an opportunity. Higher yields make US Treasuries more attractive, which is why we recently increased our exposure, hedged into local currencies. They now provide appealing income as well as useful diversification should weaker growth or renewed equity-market volatility unsettle investors.
Technology is finding its feet
Technology shares showed surprising resilience this week. Concerns about AI infrastructure spending and financing had already unsettled investors, while the departure of Nvidia CEO, Jensen Huang, added a company specific shock. Yet the broader technology market recovered despite the pressure on its most prominent AI bellwether.
Results from CoreWeave helped restore confidence. The AI cloud provider beat expectations for quarterly revenue and raised its 2026 sales outlook, providing fresh evidence that demand for computing capacity remains strong.
This gets to the heart of our view on AI. We expect the exceptional pace of growth in AI investment to slow as the spending base gets larger, but we still expect investment itself to rise. That continues to support revenue and earnings growth across the technology supply chain and is one reason why we maintain our preference for US equities.
The difficulties at Nvidia are a reminder that individual companies carry their own risks, but they do not change our view of the broader AI investment cycle. As the cycle matures, selectivity will become increasingly important.
Oil could hold one of the keys
Geopolitics remains a risk and the outlook for Iran is highly uncertain. Washington has put more emphasis on economic pressure than renewed military action, but the situation remains fluid and can change quickly, keeping oil markets sensitive to new developments.
For markets, what happens to oil may matter more than the daily geopolitical headlines. Oil prices have fallen significantly from their recent peak, easing some of the pressure on inflation. That has helped equity markets recover as investors have become less concerned about another large energy shock.
A sustained decline in oil would reinforce this effect. It would ease inflation, improve household purchasing power and give central banks more room to manoeuvre. It would also support our view that markets may be pricing more Fed tightening than will ultimately be necessary.
Geopolitical uncertainty, sticky inflation and rapid advances in AI continue to pull markets in different directions. Looking through that noise, we remain moderately constructive. Global growth remains solid, earnings are growing and investment continues to support economic activity. Over time, broader AI adoption should provide an additional boost to productivity and earnings.
This week
Can the AI trade keep earning investors’ confidence?
The coming week is relatively light on major economic releases, but it could give investors a clearer view of the two forces now shaping markets: the durability of AI demand and the likely path of interest rates.
Nvidia reports third-quarter results on Tuesday after a turbulent week. Investors will be looking beyond the headline numbers for evidence that demand for AI infrastructure remains as strong as recent industry results suggest, as well as clarity on leadership, strategy and financing following Jensen Huang’s departure.
Anthropic’s long-awaited initial public offering follows on Thursday. The company behind Claude is set for one of the largest stock-market debuts ever. Its reception should reveal how willing investors remain to fund the AI build-out as scrutiny of valuations, spending and future returns intensifies.
The Federal Reserve minutes on Wednesday will bring the other part of the story back into focus. After stronger inflation and employment data, investors will be looking for clues about how much further policymakers believe rates need to rise. UK inflation and the final eurozone inflation reading will add to the picture.
Geopolitics remains the variable that could connect them all. Donald Trump’s trip to Asia for talks involving Xi Jinping and Vladimir Putin will draw attention, but markets will be particularly alert to any development around Iran that changes the outlook for oil. A sustained move in energy prices could influence inflation, the Fed and investor confidence well beyond the week ahead.
Important Information
Information correct as of 16 November 2026.
This document is designed as marketing material. This document has been composed by Brown Shipley & Co Ltd ("Brown Shipley”). Brown Shipley is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and the Prudential Regulation Authority. Registered in England and Wales No. 398426. Registered Office: 2 Moorgate, London, EC2R 6AG.
This document is for information purposes only, does not constitute individual (investment or tax) advice and investment decisions must not be based merely on this document. Whenever this document mentions a product, service or advice, it should be considered only as an indication or summary and cannot be seen as complete or fully accurate. All (investment or tax) decisions based on this information are at your own expense and at your own risk. You should (have) assess(ed) whether the product or service is suitable for your situation. Brown Shipley and its employees cannot be held liable for any loss or damage arising out of the use of (any part of) this document.
The contents of this document are based on publicly available information and/or sources which we deem trustworthy. Although reasonable care has been employed to publish data and information as truthfully and correctly as possible, we cannot accept any liability for the contents of this document, as far as it is based on those sources.
Investing involves risks and the value of investments may go up or down. Past performance is no indication of future performance. Currency fluctuations may influence your returns.
The information included is subject to change and Brown Shipley has no obligation after the date of publication of the text to update or amend the information accordingly. Accordingly, this material may have already been updated, modified, amended and/or supplemented by the time you receive or access it.
This is non-independent research, and it has not been prepared in accordance with legal requirements designed to promote the independence of investment research and is not subject to any prohibition on dealing ahead of the dissemination of investment research.
All copyrights and trademarks regarding this document are held by Brown Shipley, unless expressly stated otherwise. You are not allowed to copy, duplicate in any form or redistribute or use in any way the contents of this document, completely or partially, without the prior explicit and written approval of Brown Shipley. Notwithstanding anything herein to the contrary, and except as required to enable compliance with applicable securities law. See the privacy notice on our website for how your personal data is used (https://brownshipley.com/en-gb/privacy-and-cookie-policy).
© Brown Shipley 2026