Is it time to ask tougher questions?
5 mins to read this article

What matters to you in 30 seconds
- Investors are becoming more sensitive to risks that were easier to overlook when markets were rising, from the financing of Artificial Intelligence (AI) investment to government debt and political uncertainty.
- This is creating greater differences between companies, sectors and countries, rather than a broad retreat from markets.
- We still see reasons to be positive about markets but think this is the time to ask tougher questions about where the risks are, and which are worth taking.
Chart of the weeK
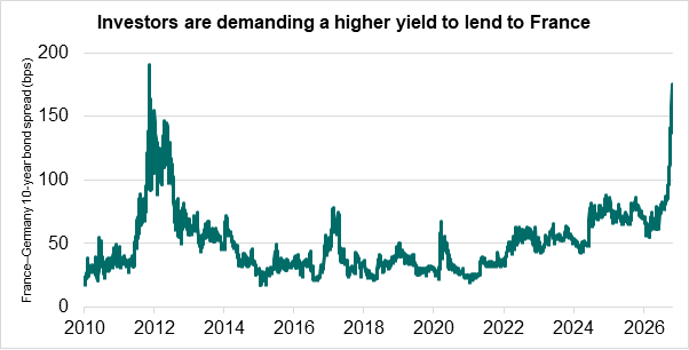
Source: In-house research, Bloomberg
Investors are looking more closely at what lies beneath
The global economy remains resilient, but investors are finding more reasons to look beneath the surface.
Last week offered several examples. Questions about the growing use of debt to finance AI infrastructure weighed on technology shares. Renewed attacks in the Middle East pushed Brent crude above USD 115 a barrel. And in France, political uncertainty added to longstanding concerns about the country's public finances.
These may appear to be separate issues, but the market response points to a common theme. Investors are becoming more selective about where they are prepared to take risk.
In equity markets, some investors took profits in technology, semiconductor and AI infrastructure companies, while money moved towards healthcare, consumer staples and financials. We don’t see this as a retreat from equities. It’s more that the questions being asked are becoming more demanding as the AI investment cycle has grown more capital intensive: how will all this investment be financed, and what returns will ultimately be needed to justify today's valuations?
A similar distinction is emerging between countries.
France has been particularly exposed as political uncertainty compounds concerns over its fiscal position. French equities underperformed, while its government bonds came under considerable pressure. The French 10-year yield rose above 5% and the gap with equivalent German bonds widened to around 170 basis points, levels not seen in decades. Meanwhile, demand for US Treasuries and German Bunds remained relatively well supported.
The common thread is credibility. Whether investors are considering an ambitious corporate investment programme or a government's finances, they are paying closer attention to how spending is funded and whether the prospective returns or economic outlook justify the risks involved.
Positive but selective on markets
The global economy continues to show resilience and the long-term investment cycle associated with AI remains supportive for growth and company earnings. That is why we continue to favour equities over bonds.
Recent market moves do, however, reinforce the case for being selective about where we take risk. We have been adjusting portfolios as these risks have evolved. We reduced our exposure to European equities earlier this year and, more recently, moved to a neutral position in European government bonds as fiscal and political concerns in France increased. At the same time, we have sought to preserve opportunities for growth while building in greater resilience, including through equity warrants in eligible portfolios and reduced exposure to US corporate credit.
We therefore remain positive on markets, while recognising that an environment of higher oil prices, political uncertainty and rising financing needs is likely to produce clearer distinctions between winners and losers.
This week
A difficult choice for central banks
The same forces making investors more selective are also making life harder for central banks.
Oil above USD 112 keeps inflation firmly in the conversation. At the same time, higher bond yields and geopolitical uncertainty risk can weigh on economic growth. For the US Federal Reserve (Fed) and European Central Bank (ECB), that makes the next interest-rate decision less straightforward.
We do not expect either central bank to raise rates this week. For the Fed, attention is likely to turn instead to how it balances these competing risks and whether another increase could still come before the end of the year.
The ECB has another reason to be patient. Rising Eurozone bond yields have already tightened financial conditions, particularly in France. We therefore expect it to wait until December, when updated economic forecasts should provide a clearer picture of inflation and growth. We also think direct intervention in French bond markets remains very unlikely.
So, investors may learn more this week from the way central banks describe these risks than from the decisions themselves.
This week will also deliver the quarterly earnings results for large tech companies such as Microsoft, Alphabet and Amazon. Collectively, they should give a good read on the question currently dominating markets: is the extraordinary AI capex cycle translating into sufficient revenue and earnings growth?
Important Information
Information correct as of 26 October 2026.
This document is designed as marketing material. This document has been composed by Brown Shipley & Co Ltd ("Brown Shipley”). Brown Shipley is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and the Prudential Regulation Authority. Registered in England and Wales No. 398426. Registered Office: 2 Moorgate, London, EC2R 6AG.
This document is for information purposes only, does not constitute individual (investment or tax) advice and investment decisions must not be based merely on this document. Whenever this document mentions a product, service or advice, it should be considered only as an indication or summary and cannot be seen as complete or fully accurate. All (investment or tax) decisions based on this information are at your own expense and at your own risk. You should (have) assess(ed) whether the product or service is suitable for your situation. Brown Shipley and its employees cannot be held liable for any loss or damage arising out of the use of (any part of) this document.
The contents of this document are based on publicly available information and/or sources which we deem trustworthy. Although reasonable care has been employed to publish data and information as truthfully and correctly as possible, we cannot accept any liability for the contents of this document, as far as it is based on those sources.
Investing involves risks and the value of investments may go up or down. Past performance is no indication of future performance. Currency fluctuations may influence your returns.
The information included is subject to change and Brown Shipley has no obligation after the date of publication of the text to update or amend the information accordingly. Accordingly, this material may have already been updated, modified, amended and/or supplemented by the time you receive or access it.
This is non-independent research, and it has not been prepared in accordance with legal requirements designed to promote the independence of investment research and is not subject to any prohibition on dealing ahead of the dissemination of investment research.
All copyrights and trademarks regarding this document are held by Brown Shipley, unless expressly stated otherwise. You are not allowed to copy, duplicate in any form or redistribute or use in any way the contents of this document, completely or partially, without the prior explicit and written approval of Brown Shipley. Notwithstanding anything herein to the contrary, and except as required to enable compliance with applicable securities law. See the privacy notice on our website for how your personal data is used (https://brownshipley.com/en-gb/privacy-and-cookie-policy).
© Brown Shipley 2026