

Mitigating European political risk
8 mins to read this article

What you need to know
-
Growth and earnings remain supportive. The US continues to lead global growth, while the Artificial Intelligence (AI) investment cycle is supporting corporate profits. We therefore maintain a moderate overweight to equities.
-
Inflation is becoming more complicated, but this is not 2022. Higher oil prices and geopolitical tensions may push inflation higher in the near term, causing some central banks to raise rates again, but this isn’t a return to the aggressive tightening cycle of 2022.
-
We have reduced European government bonds and increased US Treasuries. Political risks around the French and Italian elections in 2027 are becoming more important and we do not believe these risks are fully reflected in European government bond markets.
Note: Any reference to portfolio positioning relates to our flagship core discretionary portfolios. Clients invested in other strategies, or in bespoke and advisory portfolios, should consult their Client Advisor.
Why politics matters more today
The global economy remains resilient, and earnings growth continues to be supported by healthy demand, particularly in the US. Yet the main change in our thinking this month is not about growth. It is about political risk.
France’s 2027 presidential election is likely to be an important test for markets. Concerns around fiscal sustainability, political fragmentation and the future direction of economic policy in the Eurozone are already influencing market sentiment.
Italy and Spain will also hold elections in 2027 and November 2026, respectively, potentially adding to the political uncertainty surrounding European government bonds.
Markets have already reflected some of these concerns. French equities and government bonds have underperformed, and investors are paying closer attention to risks around government debt levels in Europe. However, we don’t think the risks are fully reflected in current government bond prices.
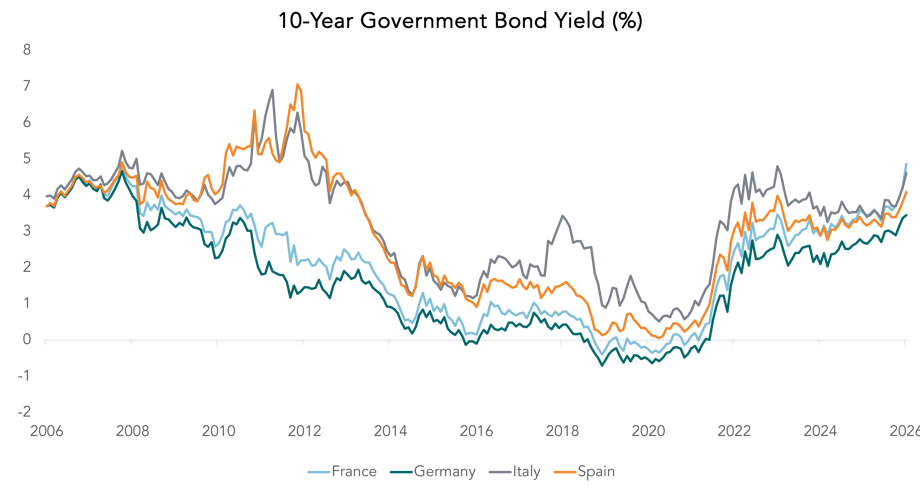
Source: In-house research, LSEG Datastream. Past performance is not a reliable indicator of future returns.
We’re changing our bond allocation
We are reducing our allocation to European government bonds from overweight to neutral. This decision is more about political and fiscal risks rather than a view on the level of yields.
While there are pockets of fiscal resilience in Europe, particularly in Germany, the Eurozone as a whole still faces difficult choices. France and other economies, including Italy and Spain, have high debt levels. This limits the room for governments to respond to economic shocks through additional spending. If uncertainty around these governments’ capacity to spend increases, investors may demand higher yields to hold their bonds, leading to falling bond prices.
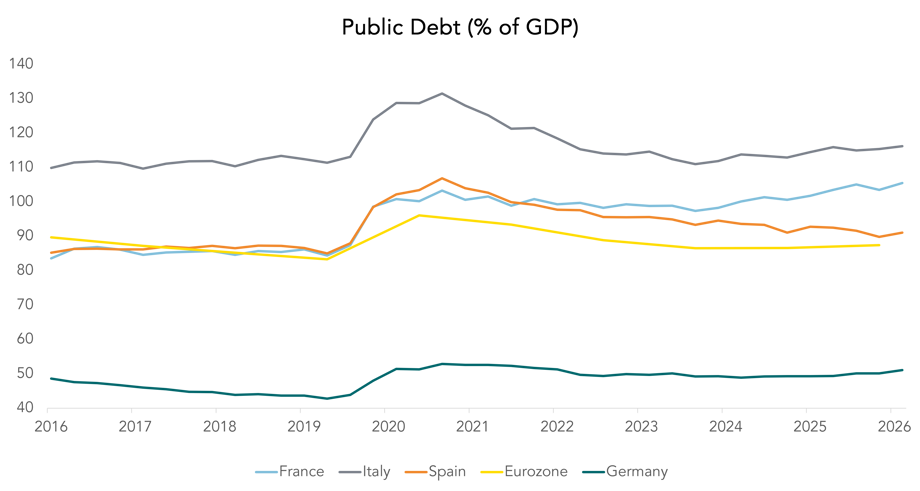
Source: In-house research, LSEG Datastream
That is the reason why we’re reducing our European government bond holdings. We’re not making a strong call on the direction of interest rates. Rather, we don’t think the rewards offered by European government bonds outweigh the risks and prefer to reduce exposure to this potential source of volatility.
Shifting towards US Treasuries
Against this backdrop, we are increasing our exposure to US Treasuries to a moderate overweight. At the same time, we are hedging our US dollar exposure in Treasuries back into euros or sterling, depending on the portfolio’s currency.
Our aim is not to target a particular income differential between the US and the Eurozone. Rather, we do this to shift part of our bond exposure towards a market where we see fewer immediate political and fiscal risks.
The US is not without political uncertainty. The upcoming midterm elections could change the balance of power in Congress and make large government spending initiatives harder to implement. Absent new expenditure initiatives, no further budget deterioration or even a moderate consolidation looks likely, though it would not necessarily rapidly reduce the US budget deficit. This could provide some support US Treasury markets.
There is also an interest rate angle. Current bond prices also reflect expectations of several further interest rate rises. Unless inflation worsens, we think the Federal Reserve (Fed) is unlikely to raise rates more than investors already expect. If geopolitical tensions ease and oil prices fall, inflation pressures could also lessen, which would provide further support to US Treasury prices.
Growth still supports equities
Although political and fiscal developments have influenced our government bond positioning, our broader investment outlook and market strategy remain relatively constructive.
The global economy continues to grow despite higher interest rates and political uncertainty, with the US providing much of the momentum. Consumer and corporate spending remains healthy, while the AI investment cycle is increasingly visible in capital expenditure, technology demand and corporate profits.
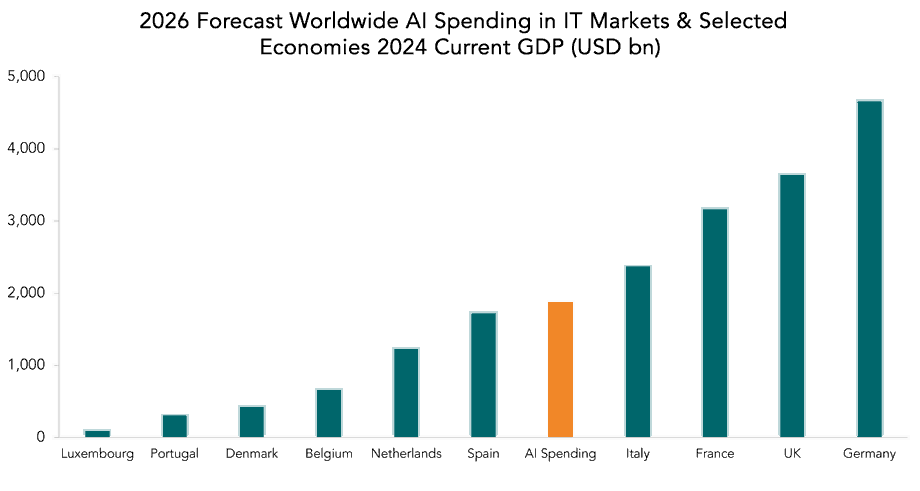
Source: In-house research, LSEG Datastream, Gartner
This is supporting earnings growth, particularly in the US and emerging markets. As a result, we continue to moderately favour equities over bonds. We also maintain a tactical overweight to gold, which can help diversify portfolios during periods of market stress and geopolitical uncertainty.
In portfolios where this is permitted, we also hold an investment designed to rise in value if US and European equity markets fall sharply. It cannot prevent losses, but it may reduce their impact during severe market declines.
Inflation is proving more persistent
The inflation problem has not disappeared, but it is no longer as broad-based problem as it was in 2022. That distinction matters because it should limit the scale and speed of any monetary policy response.
Underlying inflation, which excludes volatile components such as energy and food, is much closer to central bank targets than it was during the inflation surge of 2022. At the same time, higher oil prices and geopolitical tensions are pushing headline inflation higher, creating a difficult trade-off for policymakers.
We expect the Fed, European Central Bank (ECB) and Bank of England (BoE) to all raise interest rates in the near term. The Fed and the ECB have already started, the BoE might follow after the Autumn Budget.
However, we do not expect a repeat of the rapid tightening cycle that followed the pandemic. The drivers of inflation are different today. In 2022, economies were reopening after strict lockdowns, demand was exceptionally strong and supply severely disrupted. Today’s inflation pressures are narrower, primarily linked to energy prices and geopolitics.
Important Information
Information correct as of 6 October 2026.
This document is designed as marketing material. This document has been composed by Brown Shipley & Co Ltd ("Brown Shipley”). Brown Shipley is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and the Prudential Regulation Authority. Registered in England and Wales No. 398426. Registered Office: 2 Moorgate, London, EC2R 6AG.
This document is for information purposes only, does not constitute individual (investment or tax) advice and investment decisions must not be based merely on this document. Whenever this document mentions a product, service or advice, it should be considered only as an indication or summary and cannot be seen as complete or fully accurate. All (investment or tax) decisions based on this information are at your own expense and at your own risk. You should (have) assess(ed) whether the product or service is suitable for your situation. Brown Shipley and its employees cannot be held liable for any loss or damage arising out of the use of (any part of) this document.
The contents of this document are based on publicly available information and/or sources which we deem trustworthy. Although reasonable care has been employed to publish data and information as truthfully and correctly as possible, we cannot accept any liability for the contents of this document, as far as it is based on those sources.
Investing involves risks and the value of investments may go up or down. Past performance is no indication of future performance. Currency fluctuations may influence your returns.
The information included is subject to change and Brown Shipley has no obligation after the date of publication of the text to update or amend the information accordingly. Accordingly, this material may have already been updated, modified, amended and/or supplemented by the time you receive or access it.
This is non-independent research, and it has not been prepared in accordance with legal requirements designed to promote the independence of investment research and is not subject to any prohibition on dealing ahead of the dissemination of investment research.
All copyrights and trademarks regarding this document are held by Brown Shipley, unless expressly stated otherwise. You are not allowed to copy, duplicate in any form or redistribute or use in any way the contents of this document, completely or partially, without the prior explicit and written approval of Brown Shipley. Notwithstanding anything herein to the contrary, and except as required to enable compliance with applicable securities law. See the privacy notice on our website for how your personal data is used (https://brownshipley.com/en-gb/privacy-and-cookie-policy).
© Brown Shipley 2026